


Mitch Reznick, head of cross border credit at Federated Hermes Limited
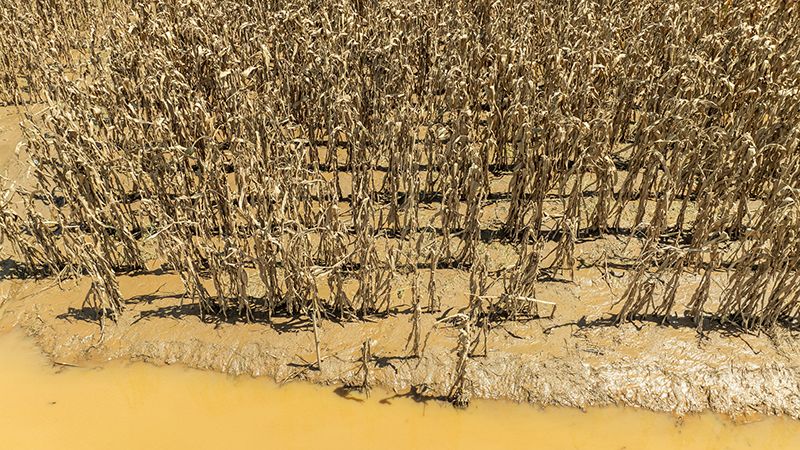
El Niño triggers changes in wind patterns along the equator that cause atmospheric anomalies. These irregularities compound the pressures placed on economic activities such as agriculture, forestry, energy, tourism, insurance, infrastructure that climate change already exerts.
While the direct impact of any weather events will be local, the effects are likely to be global as supply chains in agriculture, materials, energy and manufacturing could be impaired.
Should these physical risks come to fruition, the global effort to tame Gulf war-caused inflation will be made even more challenging. El Niño-driven inflation is already happening in certain parts of Latin America and Asia.
This, as it works through global value chains, could add to the pressure on global interest rates. Higher rates are a headwind for economic growth; magnify the cost of capital and creates fiction for the availability of credit. These can be more painful for weaker companies. In such an environment, from an idiosyncratic perspective, understanding where the fault lines lay from triggered physical risks will be key to avoiding credit losses.
From a macro perspective, managing risk in insurance and sectors and regions most vulnerable to an elevated interest rate environment will be key to investment performance.
See also: Lack of investment in nature poses growing risks to UK businesses, experts warn
Jack Yonge, responsible investment lead at Premier Miton Investors
A “super” El Niño could provide a timely insight into both the increasing risks and opportunities associated with climate change.
For those investors willing to engage with the climate science, it may provide a source of significant future value.
The primary economic impact is likely to be agricultural. Previous El Niño episodes have caused droughts and wildfires in South East Asia, putting intense pressure on agricultural yields for staple crops and exports such as rice, palm oil and coffee. Global food commodity prices could therefore be set to rise significantly.
Fixed income investors should be alert to the potential impact on sovereign and corporate credit.
Disruption to food, transport and energy systems is likely to contribute to headline inflation, potentially exacerbating “higher for longer” interest rates. Emerging market economies may come under pressure from weaker export earnings and higher public spending, while weather-sensitive companies in the agricultural and transport sectors may experience deteriorating credit quality.
For equity investors, opportunities could emerge in cooling technologies, water infrastructure, irrigation technology and grid modernisation. Fundamentally, companies with diversified sourcing, resilient infrastructure and strong management of physical climate risks will likely be better positioned.
Alexandra Symeonidi, senior corporate credit and sustainability analyst, William Blair Investment Management
A strong El Niño, which is expected this year, could have far-reaching implications for emerging markets.
For investors, the effects are rarely uniform; the phenomenon is likely to create winners and losers across EMs rather than produce a uniformly negative outcome.
Current forecasts point to below-average rainfall across parts of northern South America as well as Southeast Asia, while wetter conditions are expected in Turkey, North Africa and the Middle East. One potential transmission channel is power generation.
Many Andean and sub-Saharan African countries rely heavily on hydropower, leaving them vulnerable to the effects of lower rainfall, declining reservoir levels, and reduced hydroelectric output. Past El Niño events have generally had only a modest impact on hydropower generation, but a stronger event next year could increase those risks.
A second channel is inflation, particularly in countries where food accounts for a large share of consumer spending and agricultural production is sensitive to weather conditions. El Niño can also have broader economic and political implications. India, for example, depends heavily on the monsoon season to support agricultural production.
A weaker monsoon associated with El Niño could weigh on crop yields, contribute to food-price pressures, and create additional domestic and political challenges.
See also: UK businesses prioritise affordability over ESG despite support for sustainable finance
Tim van den Pol, portfolio manager, Farmland, at Van Lanschot Kempen
A strong El Niño usually brings drier weather to eastern Australia, South-East Asia, India and southern Africa, and wetter weather to Argentina and southern Brazil.
That lifts prices for rice, sugar, palm oil and wheat. El Niño is only one of several pressures pushing food prices up.
Energy and fertiliser cost more, tighter immigration has raised wages, the climate is changing quickly, and interest rates are higher.
Those higher food prices pass along the chain, from processor to retailer to consumer. The weather also affects insurers, real estate and timberland. Farmland feels it most directly, through yields. Farmland is illiquid, so investors cannot trade the weather.
El Niño’s effects vary by region, and when it fades, often into La Niña, the pattern reverses.
The answer is to spread across regions, crops and water sources, favour land with healthy soil and secure water, and hold it as protection against inflation. For diversified investors that is not entirely negative. Shortages in one place raise the value of food grown elsewhere.
Climate matters more for returns than many investors assume. The test is how an asset performs in a bad year, not a good one.
This story was written by our sister-title, Portfolio Adviser